The First Home Scheme

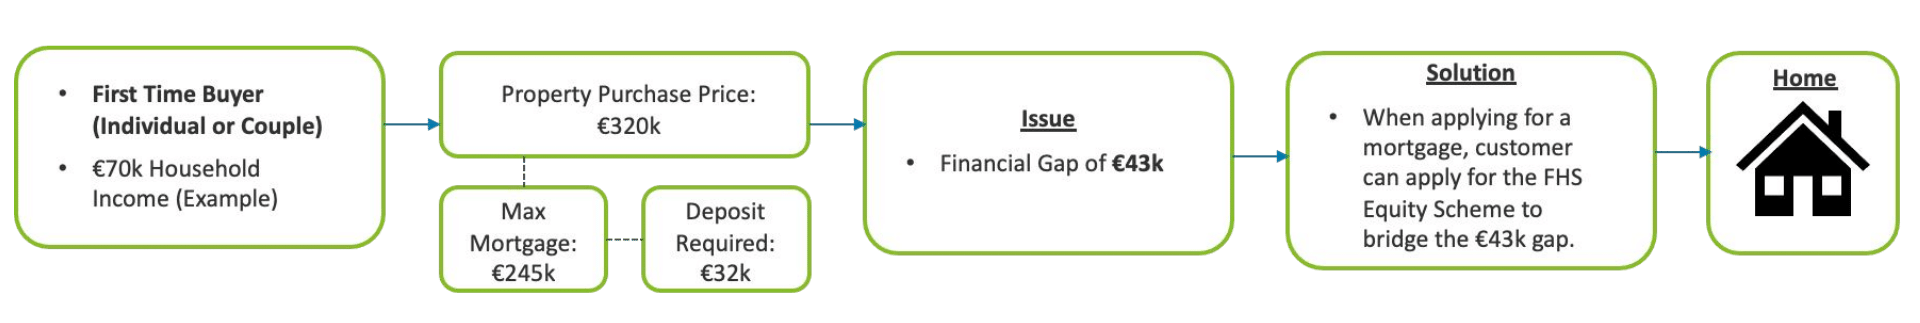
This is a shared equity scheme, bridging the gap for first time buyers and other eligible homebuyers between their deposit and mortgage, and the price of their new home.

Here are the main factors you need to keep in mind regarding the First Home Scheme in Ireland:

To be eligible for the Scheme you must:
  • Be over 18 years of age

  • Be a first-time buyer or other eligible homebuyer (see below)

  • Have Mortgage Approval with a Participating Lender (Mortgage ABC are brokers for all Participating Lenders)

  • Borrow the maximum amount available to you from one of the Participating Lenders (up to 4 times your income*)

  • Not be availing of a Macro Prudential Exception (MPE) with a Participating Lender

  • Have a minimum deposit of 10% of the property purchase price or build cost (for self-builds, equity in your site can contribute to your deposit.)

To be eligible for the Scheme the property must:

  • Be a qualifying house or apartment OR a Self-build on a privately owned site OR a house or apartment you are currently renting and residing in and now, looking to purchase having received a Notice of Termination from your landlord, as the landlord is putting the property on the market 

  • Be a property in a private development OR on a site in your name in the Republic of Ireland

  • Be your Principal Private Residence

  • Be within the local authority property price ceiling for the property type

How much funding can the FHS provide?

  • The FHS can fund up to 30% of the property purchase price or build cost (for Self-builds)

  • This amount is reduced to 20% if you are availing of the Help to Buy Scheme (HTB). Details of HTB can be found on the Revenue’s website (www.revenue.ie), and examples, including the HTB can be found in the Homebuyers Guide on the Guides/Resources page

  • The minimum equity share is 2.5% of the property purchase price or build cost (for self-builds), or €10,000, whichever is higher

First Home Scheme at a glance:

  • The FHS is a shared equity scheme

  • Available for qualifying properties

  • Local authority area price ceilings apply

    • Property price ceilings are reviewed on a biannual basis and are subject to change. Ceilings were last updated in early 2026, with increases across 17 local authority areas. Please refer to the First Home Scheme price ceiling page for the most up-to-date figures for your area.
  • Not a loan

  • Get up to 30% of the property purchase price or build cost (for self-builds)

  • Service charges apply from year six:

    • 1.75% for years 6 to 15
    • 2.15% for years 16 to 29
    • 2.85% for years 30 and over

How the Equity Share Works

The equity share provided by the First Home Scheme on day 1 will be a percentage of the property value (max available 30%, if availing of Help to Buy 20%):
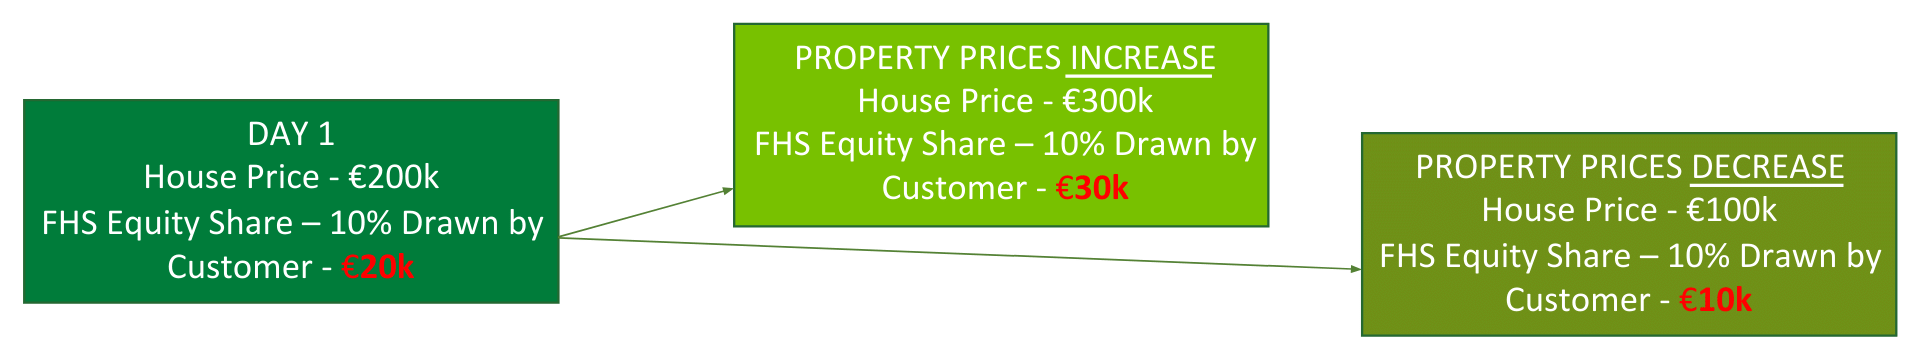
  • For example, a customer is provided with €20k from the scheme for a home costing €200k, therefore the equity share is 10%

  • After a number of years and assuming there are no redemptions in the interim, the home is now worth €300k due to property price inflation. The equity share held by the First Home Scheme is still 10%, meaning that the euro amount owed to the First Home Scheme is now €30k

  • Using the same example if house prices decease in the same period and the property is now worth €100K, the euro amount owed to the First Home Scheme is now €10k

  • From the customer’s perspective the euro amount may increase or decrease, as the equity is linked directly to the value of the home. The customer is no worse or better off, as the percentage equity remains the same throughout (this assumes they have made no redemptions over the intervening years – if they have, the equity amount owed reduces)

First home Scheme

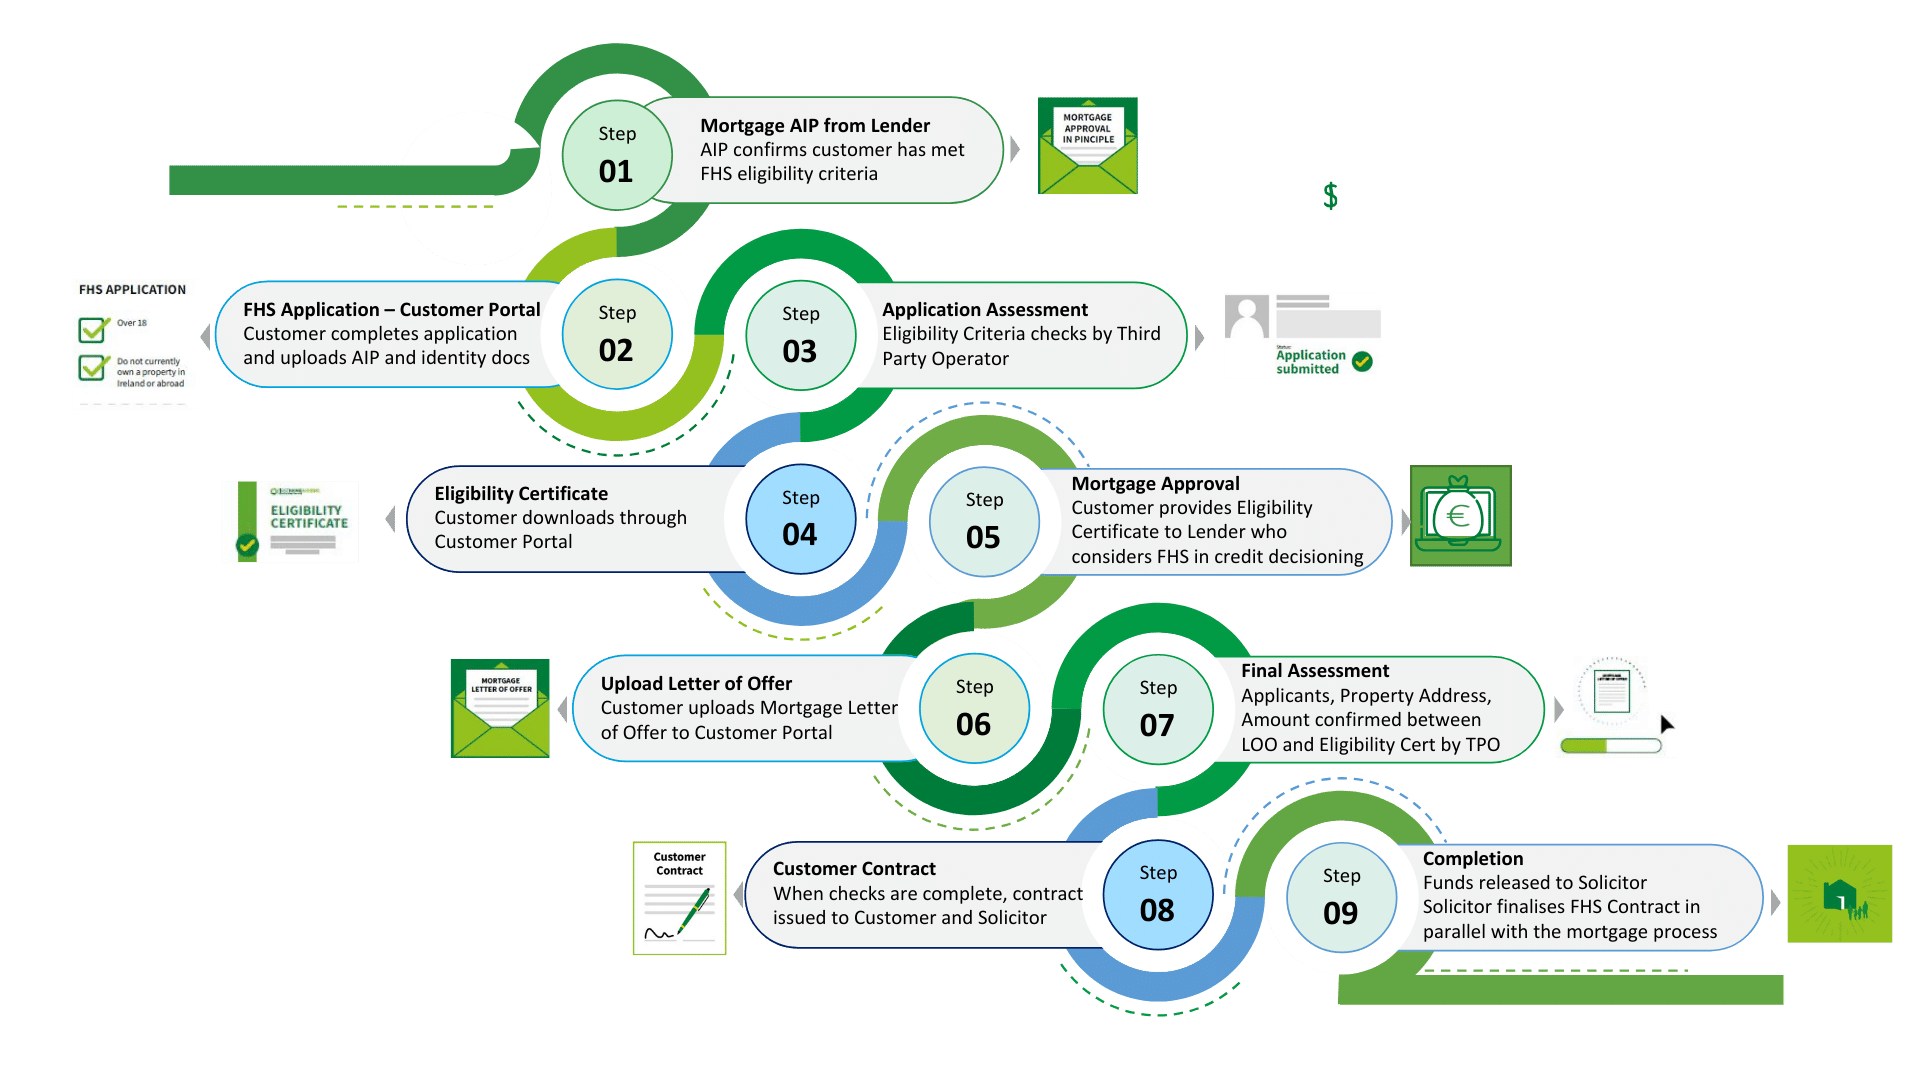
FHS Customer Journey

First home Scheme

Scheme Details:

  • There will be no interest charged (equity product)

  • After year 5 of ownership, there will be an annual service charge (sliding scale) which customers can choose to pay or roll up as part of the equity:

    • 1.75% for years 6 to 15
    • 2.15% for years 16 to 29
    • 2.85% for years 30 and over
  • The service charge is based on simple interest % of initial capital deployed and reduces as capital is redeemed

  • There are 4 scenarios under which redemption of the equity facility and charges will be required:

    • A sale of the property at any time post purchase
    • The property is no longer your PPR (Principal Private Residence)
    • You re-mortgage with a lender who is not a member of the scheme
    • The death of the owner/owners where the property is subject to probate
  • The equity can be partially or fully redeemed by the customer at any time, based on the percentage of equity held by the FHS, calculated on the value of the property at the time of redemption.

  • At the time of full or partial redemption, a valuation will be required. A valuation is valid for 12 months. The minimum redemption is 5% of the original equity amount (except for the last repayment).

  • WARNING: The First Home Scheme is not regulated by the Central Bank of Ireland and the equity product is not governed by the Central Bank and its statutory codes of conduct and/or other regulations, including the Consumer Protection Code.

  • Customers receive annual statements and can contact the FHS directly via the customer portal at firsthomescheme.ie.

For more information or case specific queries on the First Home Scheme and whether you might be eligible:

Mortgages as easy as…

With MortgageABC® by First Choice Financial Services, we have technology when you want it and people when you need them, because getting a mortgage should be as easy as…

Warning

If you do not keep up your repayments you may lose your home.

Warning

The Cost of your monthly repayments may increase

Warning

This new loan may take longer to payoff than your previous loans. This means you may pay more than if you paid over a shorter term

Warning

Purchasing this product may negatively impact on your ability to fund future needs